


Both Monefit, from the Creditstar Group, and Go & Grow, from Bondora, are among the most popular investment products in Europe. Both platforms offer high liquidity and provide investors with returns of between 6 per cent and 7.5 per cent per annum.
But how sound are the parent companies behind these platforms really, and is it worth investing given the risk involved for investors? In today’s Monefit vs. Bondora report, we examine the companies’ financial performance and analyse the legal risks investors should be aware of.
In brief:
- Both the Bondora Group and the Creditstar Group will achieve record profits in 2025.
- The legal structure differs clearly from that of Ventus Energy, as, to the best of our knowledge, Bondora and Creditstar do not operate a deposit-taking business.
- Investors in Monefit and Go & Grow do not benefit from statutory deposit protection or fixed interest rates; however, the interest rates are higher than those offered by traditional instant-access savings accounts.
- The current performance of the two parent companies suggests that investors can look forward to attractive interest rates in the future as well.
Monefit vs. Bondora: How high is the risk for investors?
Both Creditstar and the Bondora Group are two experienced players in the P2P market and operate two of the most popular platforms in Europe.
On Creditstar’s platform Monefit, investors receive up to 7.5 per cent interest with daily payouts.
On Bondora’s Go & Grow platform, investors can earn up to 6 per cent a year, with daily payouts.
The financial reports of the Bondora Group and Creditstar for the year 2025 have been publicly available for a few days now, and I have analysed both in detail.
They reveal some exciting developments that are relevant to both investors and non-investors. You can find out more about the group’s most exciting developments in my latest Monefit reviews and Bondora reviews.
Both companies are currently in a very strong financial position and reported robust profits for the past year of €13.5 million (Monefit) and €9.5 million (Bondora) respectively.
Whilst these high profits are certainly welcome, on their own they say little about the security of an investment for investors.
This is because, although high profits are initially good news, they do not automatically protect your investments: Neither Bondora nor Creditstar are contractually obliged to step in should the loan portfolio fail to generate sufficient interest.
At the same time, the record profits show that the underlying loan portfolios are currently performing well.
Today, however, we are primarily looking at the legal risks associated with the two P2P lending providers, particularly with regard to the BaFin.
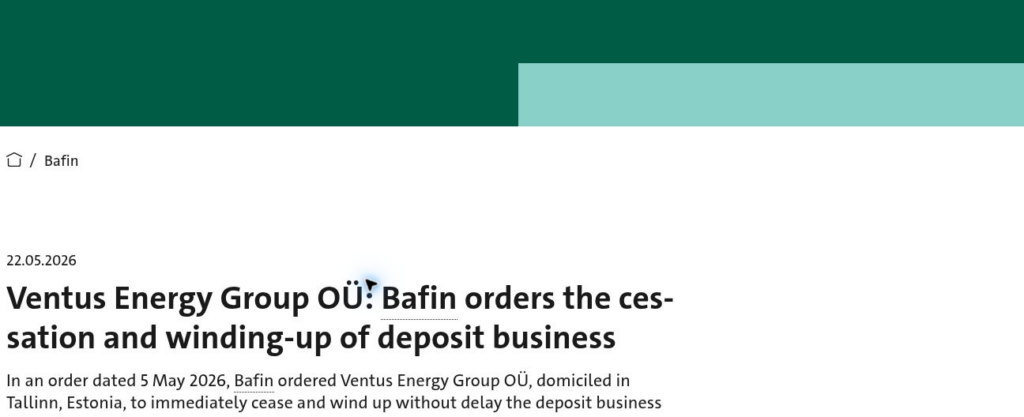
In this regard, Ventus Energy recently faced serious consequences, as the BaFin suspected the platform of conducting illegal deposit-taking business.
Now, one could argue that an investment in Monefit SmartSaver and Go & Grow bears certain similarities to a call money account – a product reserved exclusively for banks.
Such a product, however, would require a banking licence, which neither Bondora nor Creditstar currently hold. So how high is the risk for investors in Go & Grow and Monefit, and is it worth it given the current interest rate?
| Criterion | Monefit (SmartSaver) | Bondora (Go & Grow) |
| Foundation | 2023 | 2008 |
| Head office | Tallinn, Estonia | Tallinn, Estonia |
| Management | Aaro Sosaar | Pärtel Tomberg |
| Financed loan volume in 2025 (gross) | 533,9 million € | 697 million € |
| Regulation | Not regulated as a P2P platform; Creditstar is licensed and regulated in several European countries | Supervised by the Estonian Financial Supervisory Authority; not regulated under MiFID II |
| Annual Report | Yes | Yes |
| Investors | 48.000+ | 500.000+ |
| Return | Up to 7.5 % p.a. | Up to 6 % p.a. |
| Buy-back guarantee | No | No |
| Minimum investment amount | 10 € | 1 € |
| Auto-Invest | No | Yes |
| Secondary market | No | No |
| Bonus programs | Recommendations and special offers | Referral schemes and campaigns |
Comparison 1: Monefit vs. Bondora – Interest Rates
However, as mentioned above, the advantage Monefit has over Bondora is the higher interest rate.
At 1.5% more, this is significantly more attractive than Go & Grow. At first glance, that might not sound like much, but it certainly is – especially if you’re investing slightly larger sums and want to grow your money as a result.
The coronavirus pandemic led to fluctuating deposit limits at Bondora. Initially, investors could invest up to €400 per month via the platform, and this was subsequently raised to €1,000. Investors wishing to deposit more than this were only offered 4% interest.
In April 2025, this system was finally abolished and, at the same time, interest rates fell from 6.75 per cent to 6 per cent. This interest rate remains in force to this day.

With Monefit, the interest rate was slightly higher from the outset, at a minimum of 7.25 per cent, and those who invested more could earn even more. However, this model has been adapted to benefit investors, meaning that every investor now receives 7.5 per cent interest.

Exclusive Northern Finance promotional Vault on Monefit
The new Monefit app for Android and iOS is finally available and, to mark the occasion, we’ve launched an exclusive promotion in partnership with Monefit.
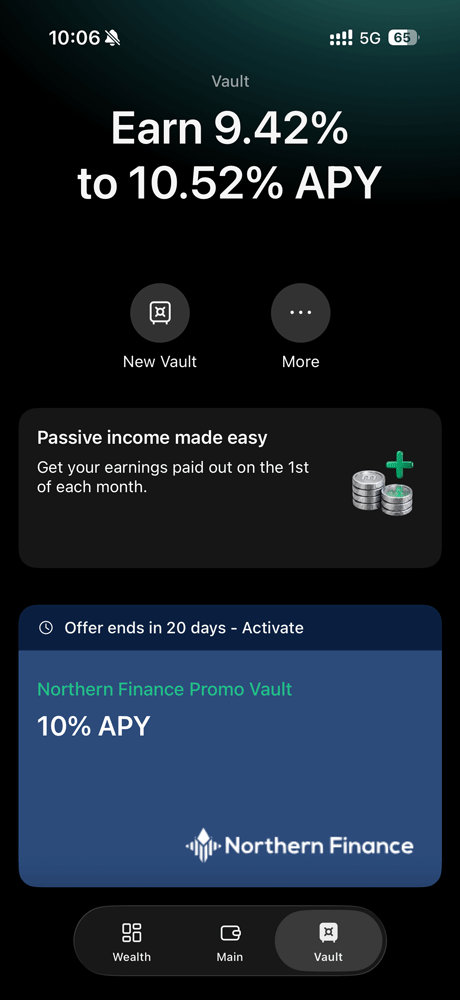
What are the benefits for you? It’s very simple: We’re increasing your interest rate for a 12-month Vault from 9.42% to 10% – with the exclusive “Northern Finance Vault”. As the name suggests, this is available exclusively to the Northern Finance community.
Here’s how to access the exclusive Northern Finance Vault:
- The 10% interest rate is reserved exclusively for the Northern Finance community.
- Click on the registration link. Only via this link will you be able to access the promotional Vault.
- In addition, you’ll receive a €5 bonus plus 0.5% on your investment during the first 90 days.
- This Vault pays out interest monthly, not daily.
- Important to note: the promotion is valid until 26 October.
Following requests from many investors, Monefit has now launched an app in addition to its web version.
You can easily find the Monefit app in the App Store and on Google Play. As it was only released a few days ago, there are no reviews available yet.
Once you’ve downloaded it, log in as usual with your credentials and you’ll be taken straight to the overview.
Good to know:
Set up two-factor authentication to provide extra protection for your account.
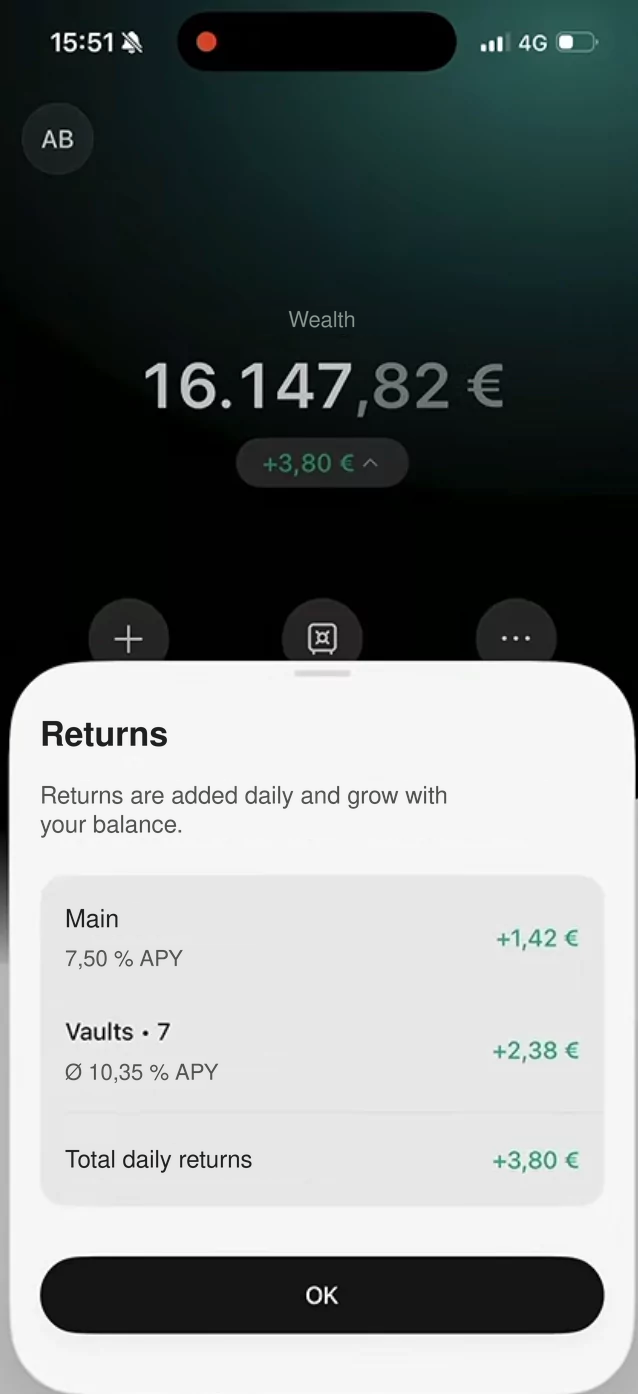
At first glance, the design of the new Monefit app is reminiscent of Revolut’s. This is definitely a positive aspect, as the app features a clear and modern layout.
It’s also handy that you can see not only the value of your deposit but also the daily interest. In my case, that’s €3.80 a day.
The features you’re used to, such as ‘Passive Income’ and ‘Auto-Invest’, are also accessible with just a few clicks. You can also easily adjust the amount you want to invest monthly via Auto-Invest using the app.
It’s also particularly handy to be able to make your withdrawals directly from the ‘Main Account’ tab. Tax statements, however, aren’t yet accessible via the app. For the time being, you still need to download them via the web version.
I can’t wait to see how the app develops in the future, and I’m proud to be the first YouTuber and blogger to have entered into an exclusive partnership with Monefit.
The bonus is available until 26 October. So make sure you claim it today!
Comparison 2: Monefit vs. Bondora – Liquidity
Monefit SmartSaver and Bondora’s Go & Grow promise their investors high liquidity and rapid payouts.
Let’s take a closer look at the financial performance of the parent companies behind them to find out whether this promise can be kept in the future.
Bondora Group Performance 2025:
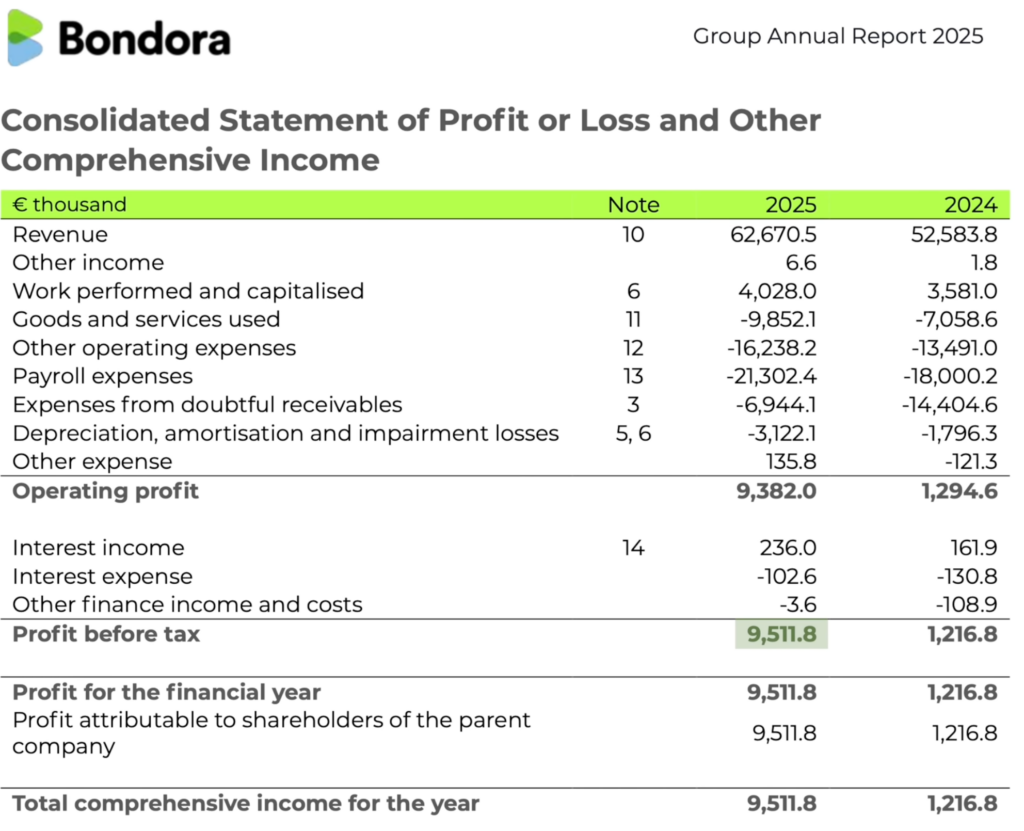
- Revenue growth: The Bondora Group’s revenue rose from €52.6 million in 2024 to €62.7 million in 2025, representing an increase of 19.2 per cent.
- Profit: The strong revenue growth has also led to a veritable surge in net profit. In 2025, the Group generated a profit of around €9.5 million – almost ten times that of the previous year, 2024 (around €1.2 million), which was marked by significant macroeconomic challenges. The cash reserve amounts to €20.4 million.
- Profitability: The return on equity (ROE) jumped from 6 per cent in 2024 to an impressive 40 per cent in 2025.
- Dividend policy: Despite the strong profit growth, the Board has decided to retain the entire net profit and not to pay out any dividends. The company wishes to finance its growth increasingly from its own resources and is therefore deliberately not pursuing a dividend policy.
Creditstar Group Performance 2025:
- Revenue growth: The Creditstar Group achieved a significant increase in revenue in 2025. This rose from €74.0 million in the previous year to €110.9 million, representing growth of 49.8 per cent. This marked the first time in the company’s history that the €100 million revenue mark had been exceeded.
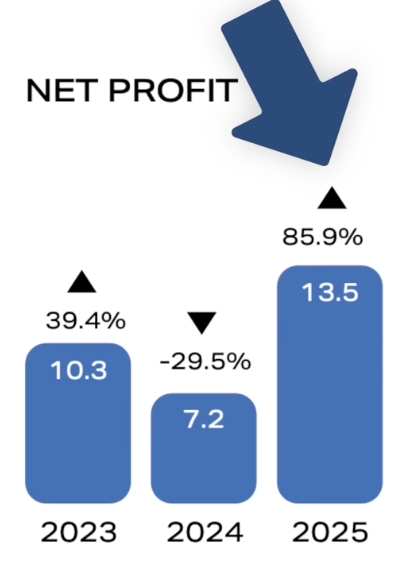
- Profit: The strong revenue growth is also reflected in the annual results. In 2025, the Group achieved a net profit of around €13.5 million, exceeding the previous year’s figure of €7.2 million, which corresponds to an increase of 85.9 per cent. At €46.8 million, the cash reserve is more than twice as high as that of the Bondora Group.
- Profitability: The return on equity (ROE) also developed very positively. It rose from 11.3% in 2024 to a strong 17.3% in the previous year.
- Dividend policy: Despite the very positive business performance, Creditstar again refrained from paying a dividend in 2025. Instead, as is the case with the Bondora Group, the profits generated remain entirely within the company.
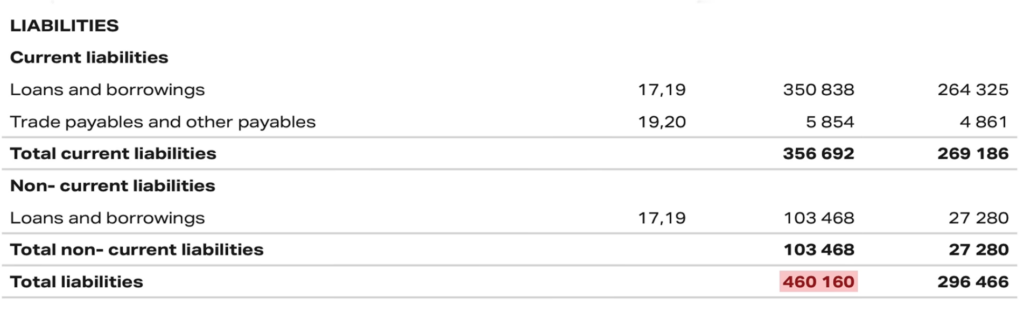
At the same time, however, Creditstar also has significantly higher debt than the Bondora Group, arising from the company’s bonds. Creditstar is therefore reliant on these higher reserves should the bonds fall due.
This is not the case with Bondora, as the company is primarily financed through its Go & Grow investment product.
Monefit is the right choice for you if you don’t need immediate access to your investment and would rather let your money work for you in the medium to long term. Especially if you don’t rely on constant liquidity in your day-to-day life, this model could well be worthwhile for you and offers more attractive interest rates in return.
Here’s how withdrawals work with Monefit compared to Bondora:
- An instant withdrawal of up to €1,000 per month is possible via SmartSaver. These smaller amounts are therefore immediately available to you, which is sufficient for many investors.
- As soon as you wish to withdraw larger amounts, you’ll need to be a little patient. Any transfer over €1,000 can still take up to 10 working days.
- For me, this is the biggest drawback compared to Go & Grow, where the entire amount lands in your account within seconds.
- This limited liquidity means that Monefit is less suitable as a short-term parking place for your money, but should instead be used for long-term wealth accumulation.
- If you’re prepared to forego maximum flexibility in exchange for a higher return, then Monefit is the better choice for your portfolio.
Comparison 3: Monefit vs. Bondora – Regulation and BaFin Risk
When you make a transfer to your Go & Grow account, Section 626 of the Estonian Law of Obligations applies. As an investor, you thereby instruct Go & Grow to manage your money, which is channelled into loans intended to generate up to 6 per cent for you annually.
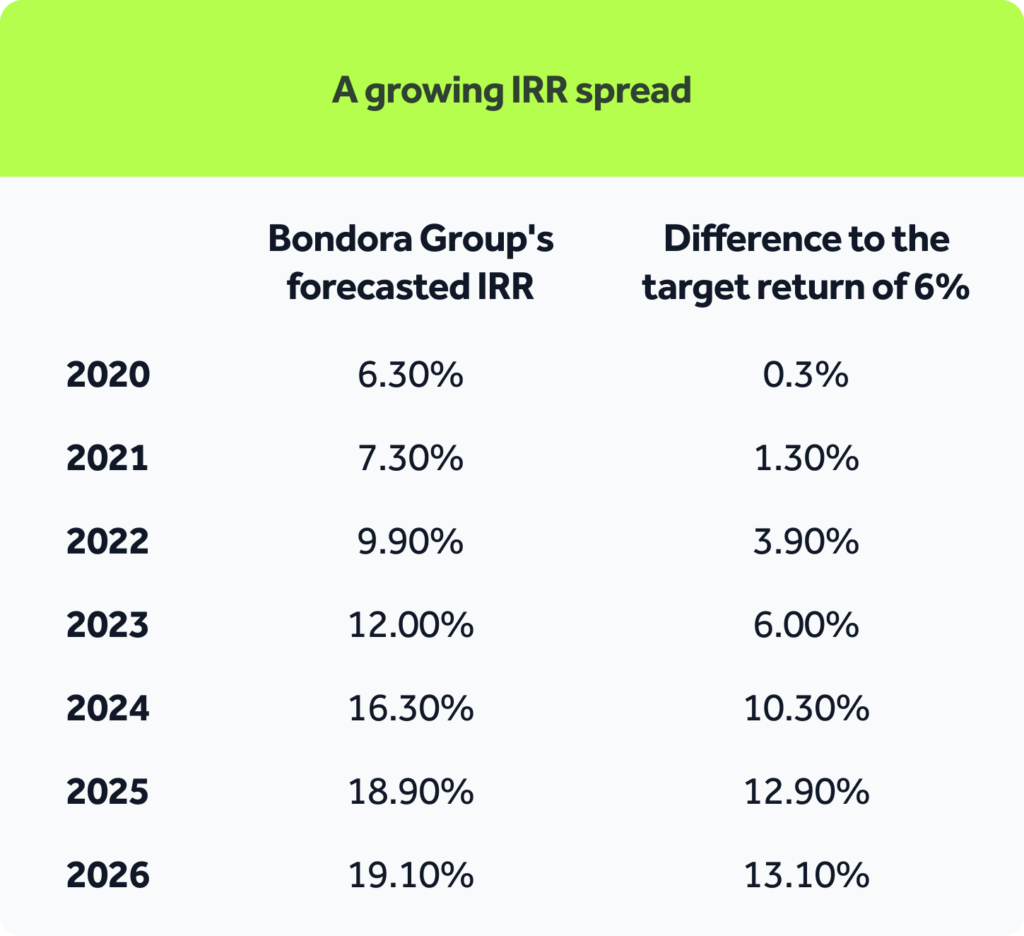
Bondora aims to safeguard this 6 per cent using the return buffer that the company has built up over recent years. The figure below shows that this will have risen to 13.10 per cent by 2026.
A look at Monefit’s terms and conditions also shows that, as an investor, you grant the company a mandate within the meaning of Section 626 of the Estonian Law of Obligations Act, in order to subsequently earn interest of up to 7.5 per cent.
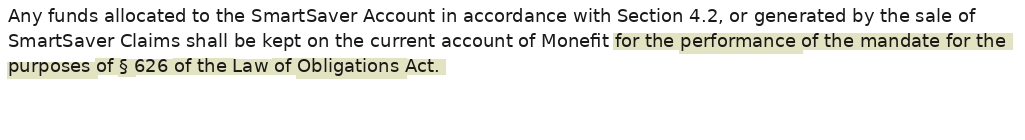
It is also important to note that, in accordance with clause 4.5 of the Terms and Conditions, the balance is used exclusively for the allocation of SmartSaver receivables and not to finance the parent company, Creditstar. The same applies to investors’ balances with Bondora.
Important: You are not granting a loan to Bondora or Creditstar; instead, you are financing the respective loan portfolio and receive a return of up to 6 or 7 per cent interest per annum in return.
This point is also the most important when considering the legal risks that investors might face with Monefit versus Bondora, and it differs quite clearly from the risks associated with Ventus Energy.
This is because, with Ventus Energy, investors lent their money directly to the company. Furthermore, the borrower’s payment obligations were at least on an equal footing (pari passu) with the claims of other creditors. A clear disadvantage for investors!
Overall, it can therefore be said that both Go & Grow and Monefit have set up a completely different system to Ventus Energy. This is because, with both companies, funds are not allocated directly to Bondora or Creditstar, but to the underlying loan portfolios.
In my view, the legal structure differs significantly from traditional deposit-taking business. However, it cannot be deduced from this whether the regulatory authorities share this assessment
Furthermore, the returns of 6 per cent and 7.5 per cent for Go & Grow and Monefit SmartSaver respectively are not guaranteed, but are directly linked to the performance of the loan portfolio.
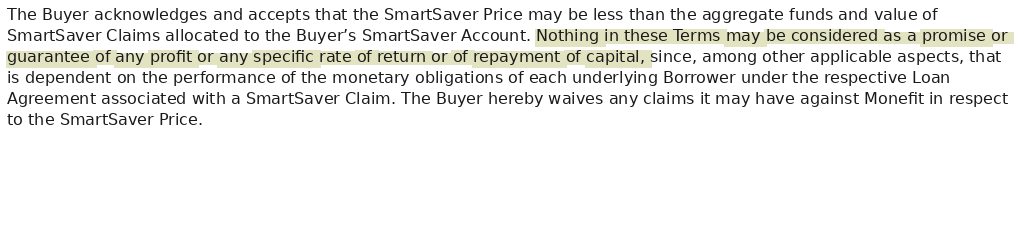
Should a crisis arise, both platforms could suspend withdrawals and, where necessary, make partial withdrawals.
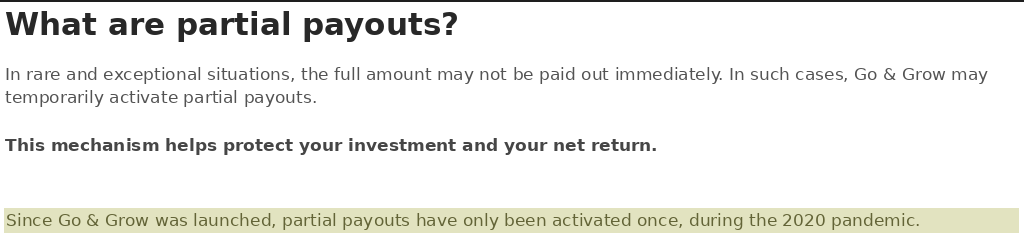
The Go & Grow website states the following: “It may not be possible to liquidate Go & Grow assets or withdraw funds immediately. In this case, we will make partial withdrawals of your total withdrawal amount.”
Fortunately, these partial withdrawals only had to be introduced once, during the Covid-19 crisis. Apart from this isolated incident, the product has performed very reliably in the past.
Bondora and Creditstar can therefore argue to BaFin that:
- the return is not guaranteed at any time
- and no loan is made to the company itself
Comparison 4: Monefit vs. Bondora – Loan portfolio
Key figures such as the proportion of active loans, payment arrears, risk categories and regional distribution provide a much deeper insight into the stability and sustainability of the business model.
Both the Bondora Group and the Creditstar Group pursue different strategies when building their portfolios, but place great emphasis on professional risk management and the continuous optimisation of their loan portfolios.
A glance at the figures from the Bondora Group’s latest loan portfolio statistics quickly reveals that the company has its loan portfolio well under control.
Not only has the company expanded its yield buffer to a robust 19.1 per cent, but it is also reporting strong figures regarding the distribution of the active loan portfolio:
- Active loans: Around 80 per cent of all loans granted remain active, whilst payment arrears have remained at a consistently low level over recent years.
- Risk classes: The vast majority of the portfolio consists of borrowers with high creditworthiness and low default risks. At the same time, the proportion of the best risk classes (AA to C) is rising steadily.
This strategy is complemented by flexible loan terms, which are tailored to the individual creditworthiness and repayment capacity of the borrowers.
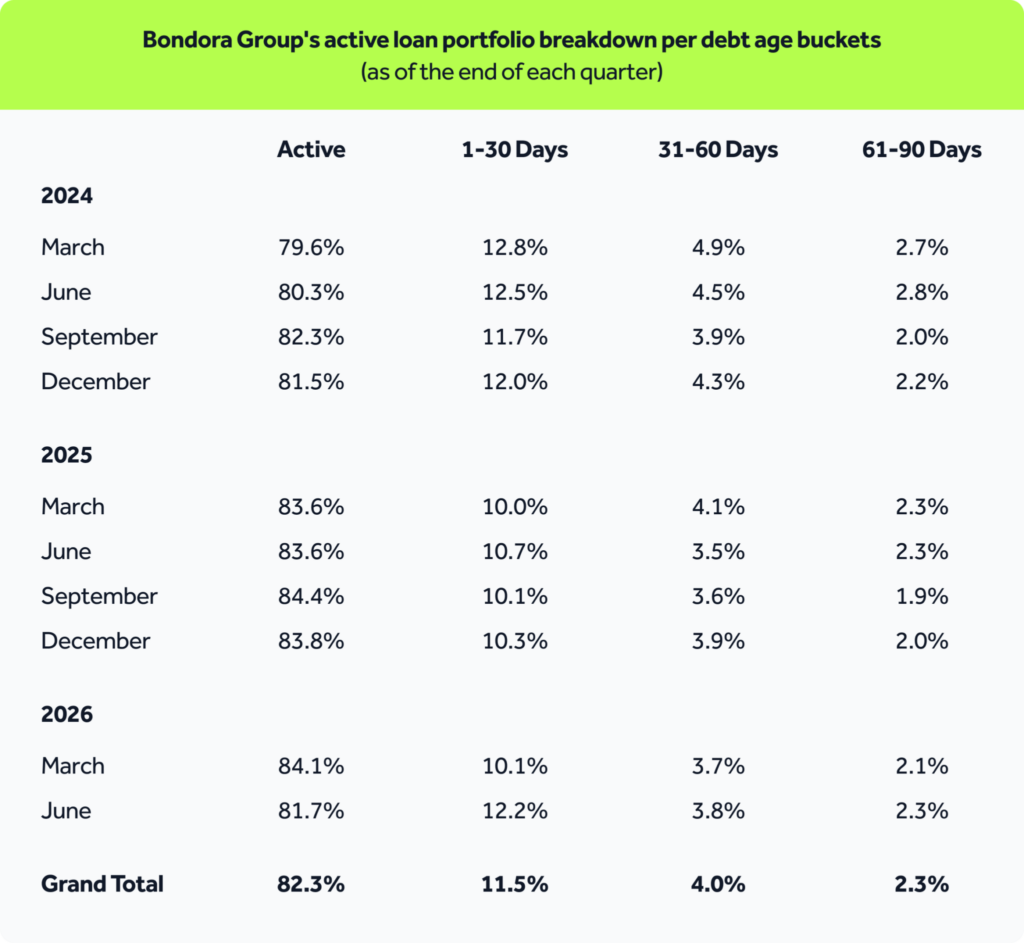
For a detailed insight into the performance of the individual markets in which Bondora operates, it’s worth taking a look at my Bondora review.
The Creditstar Group, of which Monefit is a part, is on a growth trajectory. In 2025, the loan portfolio grew by a strong 29 per cent to €533.9 million.
In addition, Creditstar has increased both credit limits and loan terms in order to attract higher-income customer groups with better credit ratings, thereby improving the overall quality of the portfolio.
But what about the repayment performance of the loans?

- Active loans: Alongside the growth in the loan portfolio, the proportion of loans repaid on time has also risen significantly. The non-delinquent portfolio increased from €321.7 million to €444.3 million.
- 31–90 days past due: There has been a slight improvement in loans that are 31 to 90 days past due.
- More than 90 days in arrears: Despite strong portfolio growth, the volume of receivables more than 90 days in arrears fell from €64.6 million to €58.9 million. This means that not only did non-performing loans decline in absolute terms, but their share of the total portfolio also decreased.
The figures from the Creditstar Group’s annual report show that the company has achieved healthy growth and, by all accounts, is set to continue developing positively.
Creditstar has not only significantly expanded its loan portfolio but has also, at the same time, improved the quality of its loans. For me as an investor, this is a positive sign and encourages me to continue investing with Monefit.
Portfolio comparison: How I invest
I’ve been with Monefit and Bondora’s Go & Grow almost from the start and have significantly expanded my portfolio on both platforms over the years.
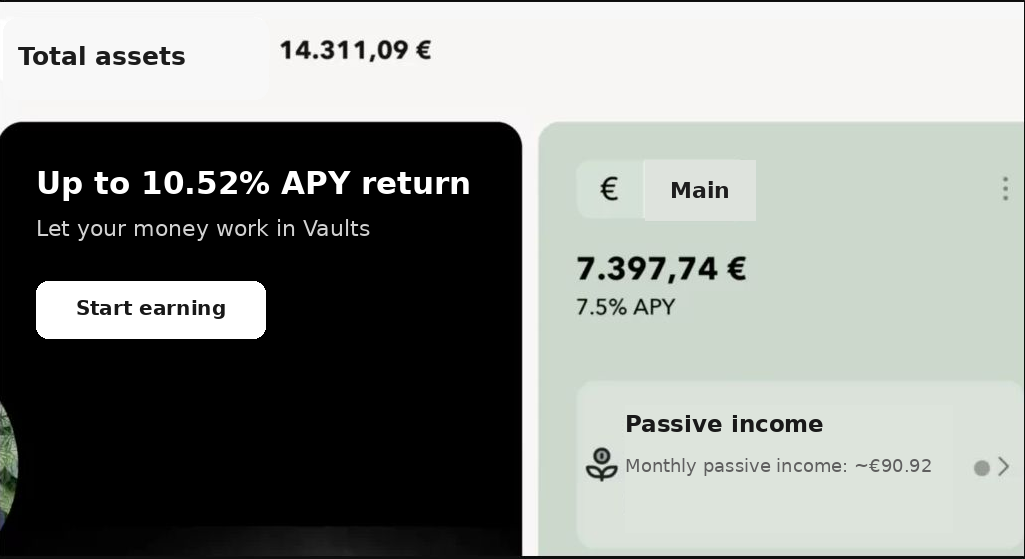
I currently have €14,300 invested with Monefit. This generates a monthly passive income of around €90.
My current balance in Bondora’s Go & Grow scheme is €12,700. This amount earns me around €2 in interest every day. Since the start of the year, I have received just under €300 in passive interest income from my Go & Grow investment.
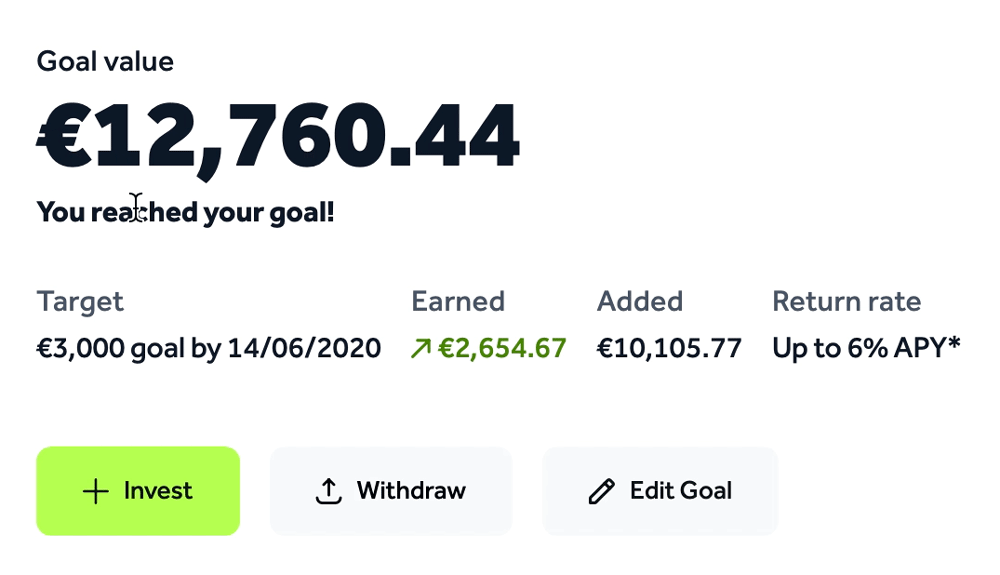
Having carried out a detailed analysis of both companies, I am satisfied with the overall financial situation of both Monefit and Go & Grow, and will therefore continue to increase my investments in the future.
Conclusion: The opportunities outweigh the risks on both platforms
Both Go & Grow and Monefit SmartSaver are exciting and, above all, high-yield investments, offering investors the chance to earn up to 6 per cent or 7.5 per cent interest per year. Furthermore, investors can withdraw their money on a daily basis, which is arguably one of the biggest advantages of both platforms.
Nevertheless, investors should always be aware of the risks involved in any investment. Neither product is as secure as a traditional call money account, although such accounts typically offer interest rates of only around 2 per cent. Investors do not benefit from deposit protection, and the return also depends on the performance of the underlying loan portfolios.
The most important legal point, however, is that the Bondora Group and Creditstar Group have structured their terms and conditions and products in such a way as to clearly distinguish themselves from deposit-taking businesses, as was the case with Ventus Energy.
And given the very reliable interest payments from both platforms, the risk-return ratio works for me here. Take a look at my Twino Flexi vs. Bondora Go & Grow review if you’d like to know more about these two platforms.
FAQ – Frequently asked questions

